Goldman Sachs Turns Bullish, Upgrading Global Stocks to ‘Overweight’ on Earnings Optimism
Goldman Sachs on Monday upgraded its three-month view on global equities to “overweight” from “neutral,” arguing that earnings growth remains supportive and that the recent pullback has made valuations more attractive heading into third-quarter earnings season. The call, reported by Reuters, brings the bank’s near-term stance in line with its bullish 12-month outlook.
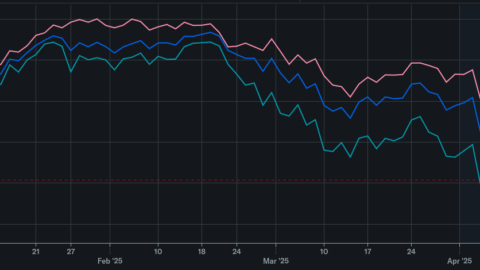
The upgrade lands as Wall Street enters its busiest stretch of the year. The S&P 500 closed Monday at 7,807.24, near record territory, with analysts expecting 25 to 30 per cent year-on-year earnings growth for the third quarter, powered by continued AI infrastructure spending. Major banks including JPMorgan Chase, Wells Fargo and Citigroup report on Tuesday, kicking off a season that will test whether corporate profits can justify elevated valuations with the 10-year Treasury yield above 5 per cent.
The barbell and the bond call
Goldman’s recommended positioning is a “barbell strategy”: global technology stocks at one end and rate-sensitive, bond-like equities at the other — both positioned to benefit if rates ease, while hedging against a tech sell-off or growth scare. Regionally, the bank stays overweight Asia and the United States and underweight Europe. Perhaps more notable is the accompanying bond call: Goldman upgraded its 12-month stance on government bonds to overweight, saying bonds should “gradually move from portfolio headwind to hedge.”
That combination — bullish on stocks and bonds together — is a bet that today’s twin pressures will fade: higher energy prices and higher interest rates. It is also a vote of confidence that the earnings season now under way will show corporate America weathering the rate shock better than the bond market’s pessimism implies.
Risks the bank itself flags
Goldman is candid about what could go wrong. Middle East supply concerns have lifted oil prices and with them inflation and higher-for-longer rate fears; mounting corporate and sovereign debt has fuelled a global bond selloff; and US midterm election uncertainty could lift market volatility from current low levels. Higher rates and energy prices, the bank says, remain the main near-term risks to equities.
For executives watching from the C-suite, the note reads as permission to stay invested through the noise — with a hedge. Whether that confidence survives contact with this week’s bank results and Wednesday’s CPI print is the question policy-driven market shocks keep forcing back onto the agenda. Goldman’s answer, for now: the pullback is the opportunity.