Taiwan Semiconductor Manufacturing Company delivered a record third quarter on October 8, reporting revenue of approximately NT$1.494 trillion — about $46.7 billion — as relentless demand for artificial intelligence chips kept its factories running at full tilt.
The figure, compiled from TSMC’s monthly disclosures, rose roughly 50 percent from the same quarter a year earlier and exceeded analysts’ average estimate of about NT$1.46 trillion. It also topped the company’s own guidance range of $44.6 billion to $45.8 billion. September revenue alone reached NT$511.86 billion, up 54.6 percent year over year, while January-to-September sales climbed 41.1 percent.
The numbers set the stage for TSMC’s full third-quarter earnings call on October 15, when investors will get the other half of the story: profitability. According to a Reuters survey, analysts expect quarterly net profit of roughly NT$740.8 billion, up about 64 percent from last year. The market’s focus, analysts say, will be on gross margins — guided at 65 to 67 percent — and whether TSMC can protect its unusually high pricing power while ramping its newest 2-nanometer chips.
High-performance computing, which covers data-center processors and AI accelerators, accounted for 66 percent of TSMC’s second-quarter wafer revenue. The company manufactures chips designed by Nvidia, Broadcom, AMD and Apple, making its results the clearest read on the health of the AI hardware boom.
Management has also raised its 2026 capital expenditure budget to between $60 billion and $64 billion, saying customers are asking the company to ramp capacity faster. When one supplier controls most of the world’s advanced chipmaking, analysts note, its margins reveal something rarer than demand: how much of the AI boom’s profit the factory itself keeps. October 15 will test exactly that.
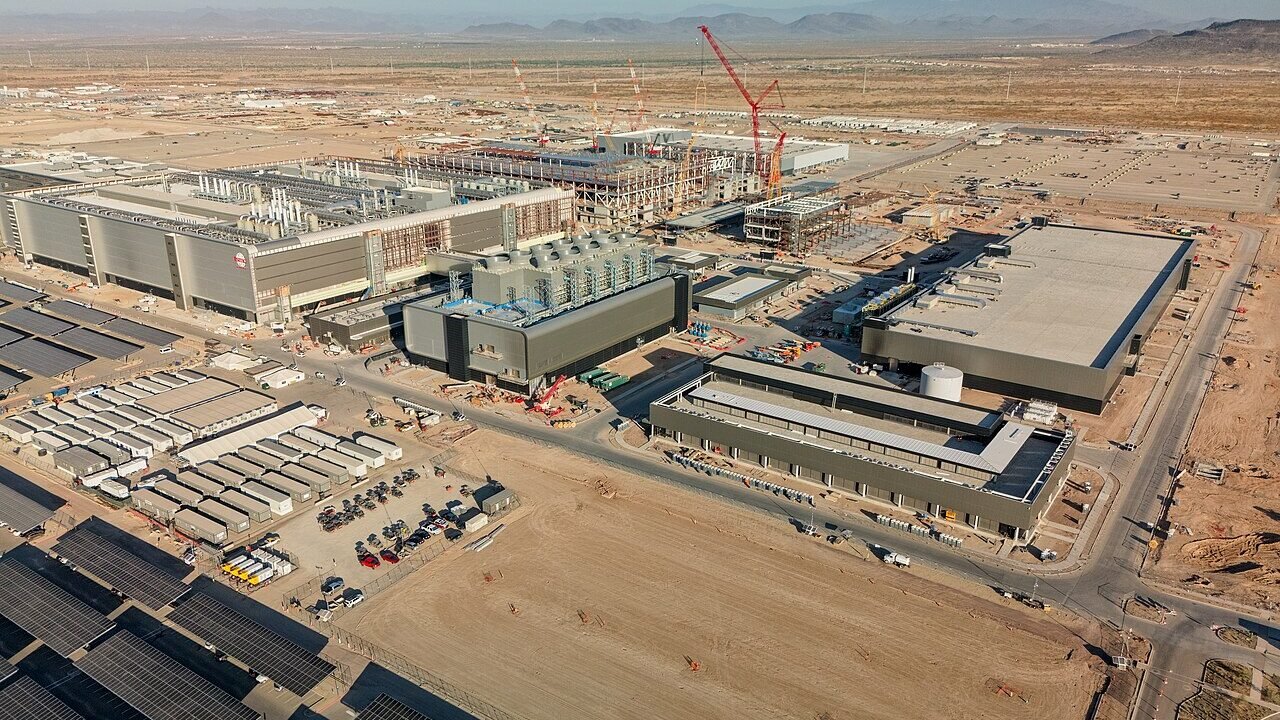
The October 15 call will also be watched for any update on the company’s expanding American manufacturing footprint, where new fabrication plants are rising to meet customer demand for domestic chip supply.